Free · France
What a Micro-Entrepreneur Really Is
A simpler regime is not a separate company—or a promise of easy income
Someone says they are a micro-entrepreneur. That tells you something about the framework in which they work, but not whether their business is profitable, whether a particular activity is authorised, or whether the arrangement suits you. The name is easiest to understand by separating three questions: who carries on the business, how its tax and social contributions are calculated, and whether the activity makes practical sense.
This is a conceptual introduction, checked against official French guidance on 29 October 2026. It is not a personal tax calculation, a registration walkthrough or a recommendation to choose this regime. Activity, residence and individual circumstances can change the answer; verify your case with the appropriate authority or a qualified adviser before committing.
First separate the legal form from the regime
Service Public describes a micro-entrepreneur as an individual entrepreneur operating in their own name under simplified tax and social arrangements. It does not create the separate legal personality that a company does. The official overview also explains that incorporation-style requirements such as company articles and share capital do not apply in the same way. Service Public, overview verified 16 October 2026.
The important distinction is not “small person versus large company.” It is legal form versus operating regime. An entreprise individuelle is the legal framework; the micro arrangements simplify specified tax and social rules within the relevant conditions. “Simplified” describes those arrangements. It does not certify your business idea, remove every obligation or turn money received into a salary.
The label auto-entrepreneur still appears on the official Urssaf portal. Seeing that older familiar wording does not by itself mean you have reached a different type of business. Service Public explicitly notes its continued use by Urssaf. Service Public, distinction explained, 23 July 2026.
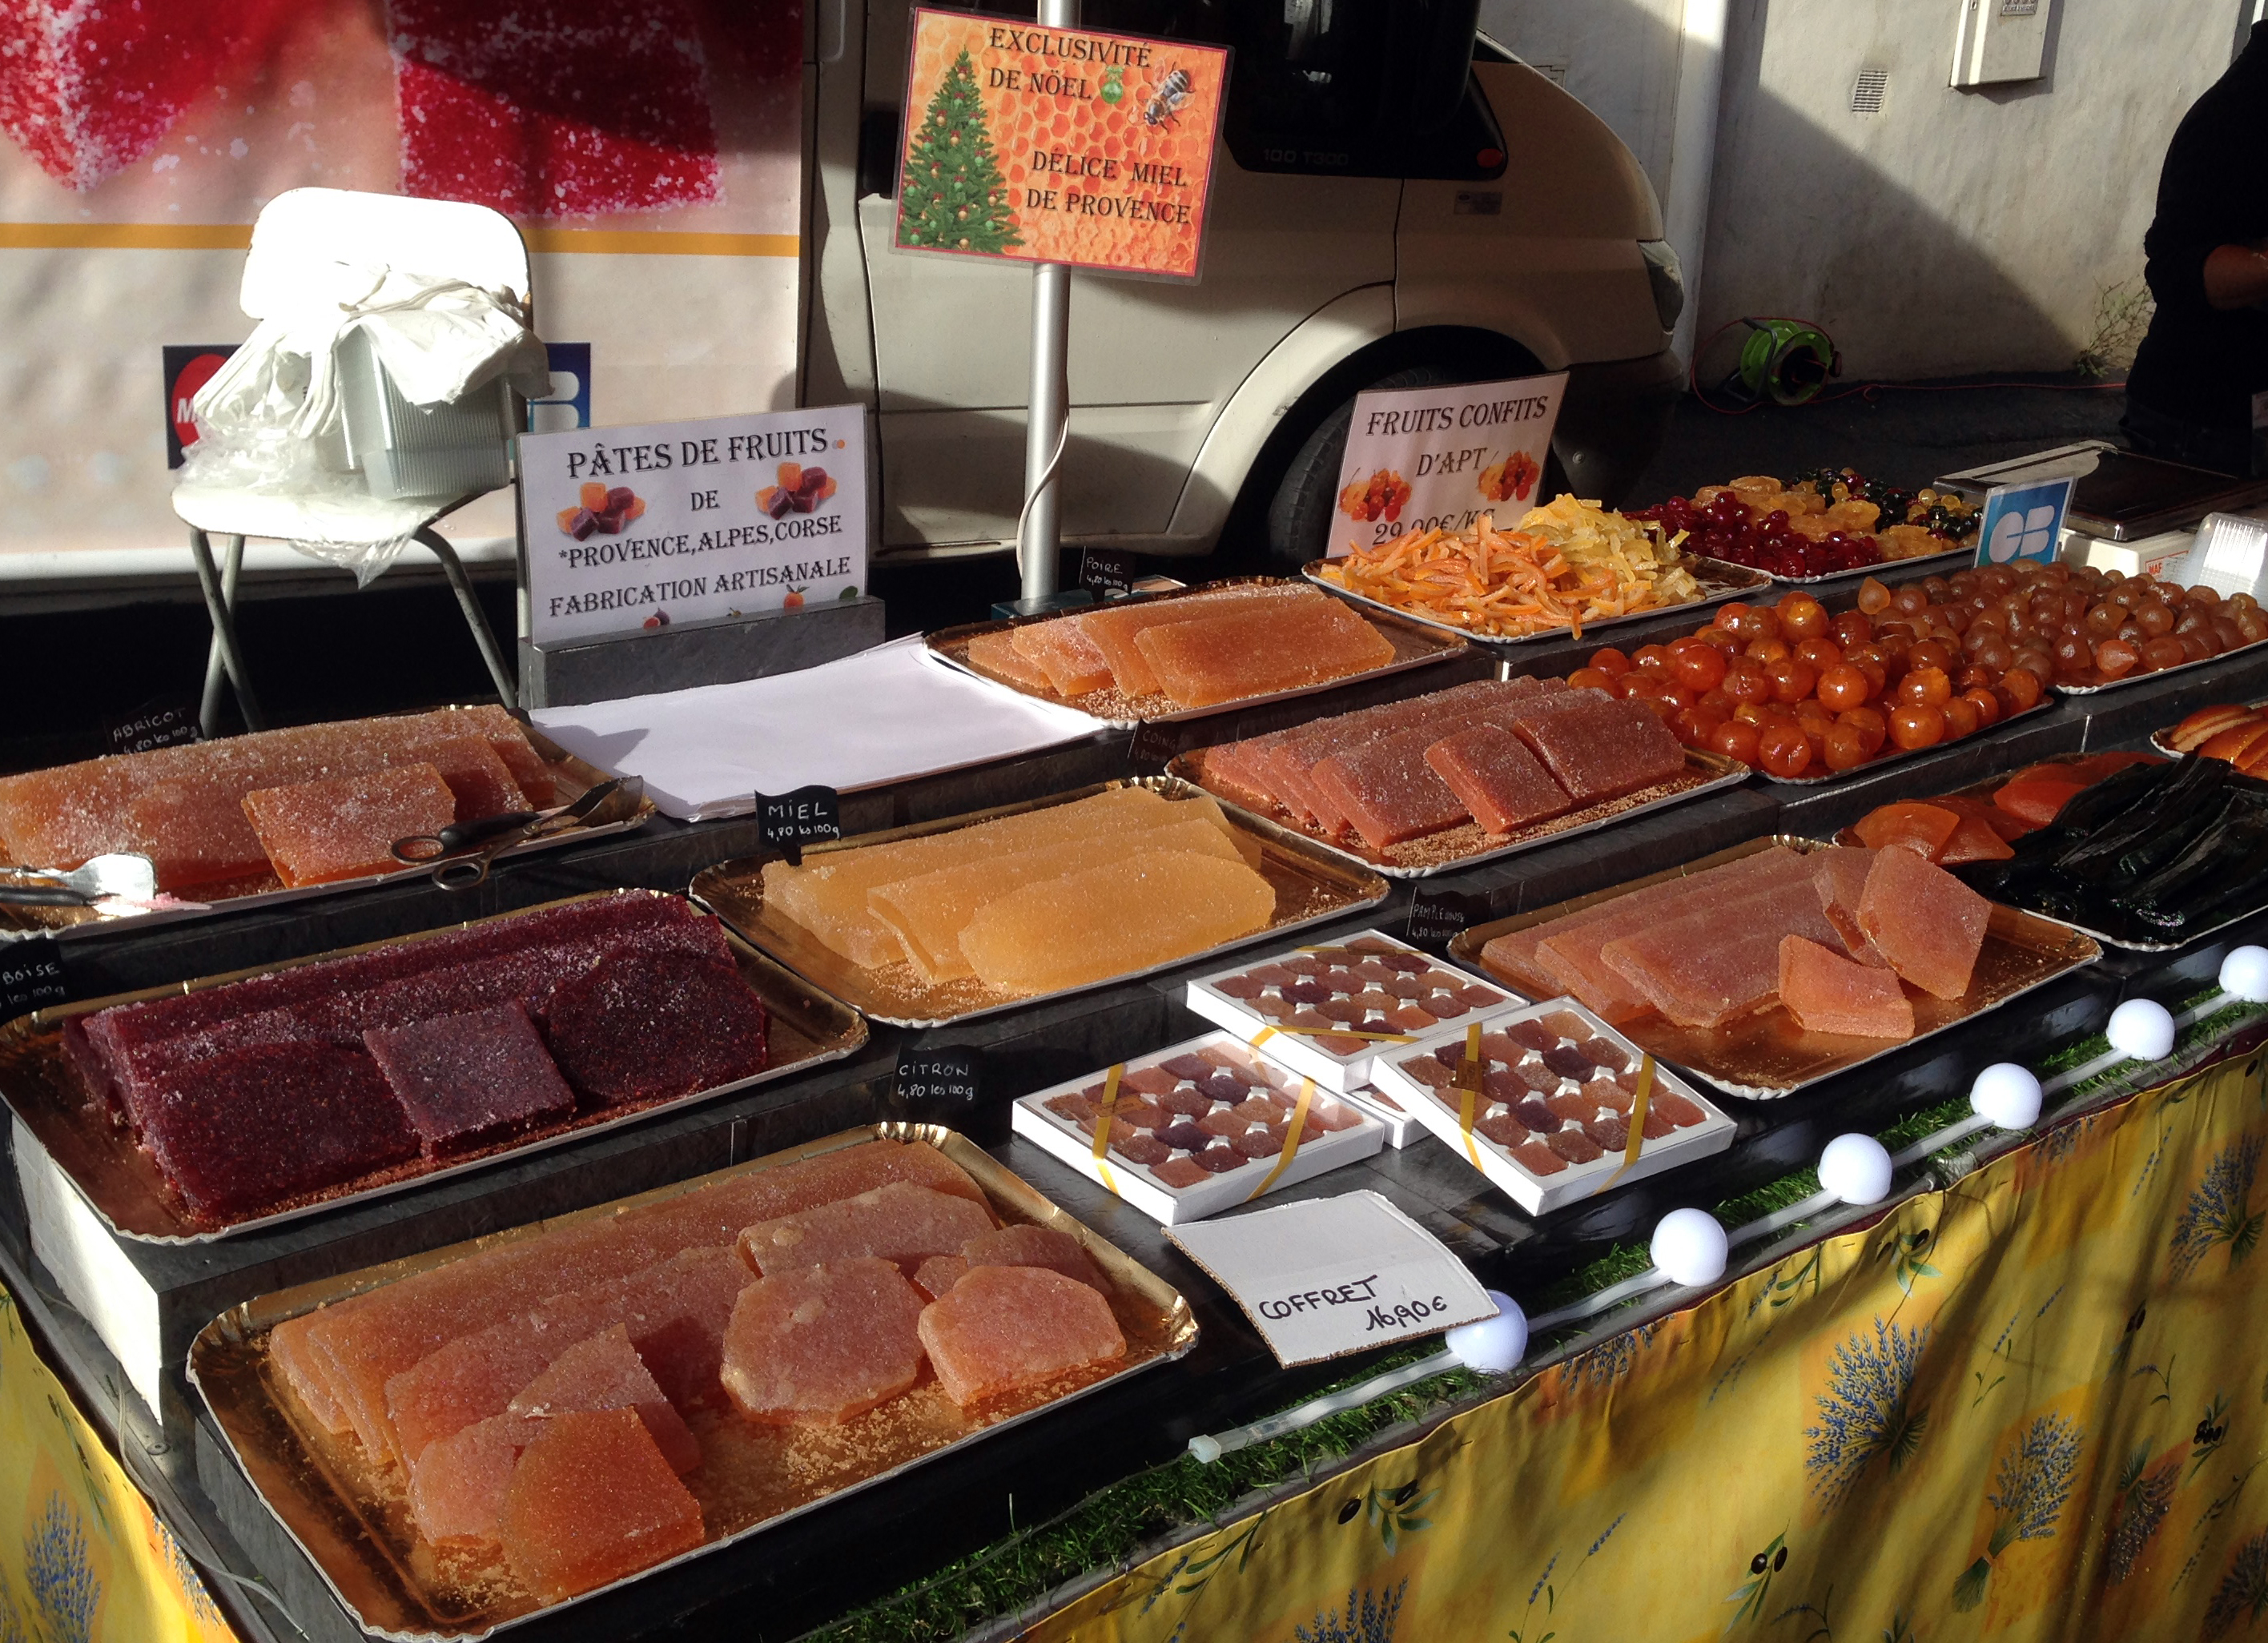
Visible commercial activity does not reveal an operator's legal form, registration or tax regime. This Apt stall photograph does not identify the business or anyone pictured as a micro-entrepreneur, and does not establish current prices. Photo: Jula2812, 30 December 2017, original record, CC BY-SA 4.0; unchanged image, displayed at reduced size.

Turnover is not the money you can freely spend
A customer payment, a business expense and the amount left for personal use are different things. The simplified regime does not make rent, materials, travel or equipment disappear from your real budget.
Under the standard micro-fiscal approach described by Service Public, business costs are represented for income-tax calculation through a flat-rate allowance rather than deduction of their actual amount. The micro-social calculation uses turnover with a rate depending on the activity. These are distinct calculations, not one universal “tax rate.” Options and individual circumstances need separate checking. Service Public, tax and social distinction.
Fictional example: Camille receives €1,000 from customers and spends €400 on materials and other business needs. The difference is €600 before considering social contributions, tax and any other obligations. It is not a net-income calculation, and it is not an instruction to declare €600 instead of the required turnover figure. The example only shows why the headline amount received is not the same as spendable income.
For a business with significant costs, that distinction deserves attention before choosing a regime. A simple declaration mechanism and a suitable economic model are two different questions.
“No sales this period” does not mean “nothing to declare”
The official declaration service states that even turnover of zero must be declared. Its workflow distinguishes recording the declaration from making the associated payment. Check the actual deadline and period in the official system rather than assuming that an inactive month suspends your obligations. Service Public, declaration service verified 8 April 2026.
This is a useful everyday distinction: a declaration records what happened; a payment settles what is due under the applicable rules. A zero figure may still need to be recorded. Nor should “zero turnover” be treated as a promise that every possible business cost or obligation is zero.
Keep evidence of what was submitted and when. Do not confuse a draft entry, a saved calculation or a message from a private service with confirmation that an official declaration was completed.
There is more than one threshold question
People often speak of “the micro threshold” as if one number answered everything. It does not. The tax administration explains that the thresholds for the micro regime are not aligned with those for the VAT exemption: a business under the micro regime can still be liable for VAT. It also distinguishes leaving a tax regime from changing legal form. Impots.gouv.fr, updated 15 October 2026.
This article deliberately does not offer a single threshold or rate to memorise. The useful habit is to identify the activity category, the relevant year, the tax or social question, and the official rule being applied. A figure copied from a different year or activity can be precise and still be wrong for your question.
A four-question card before you choose
| Question | What to establish, rather than assume | |---|---| | What will I actually sell or do? | A clear activity description, with any qualifications, authorisations or insurance requirements checked separately | | Which framework is being discussed? | Legal form, tax regime, social regime and VAT position kept distinct | | What will the activity cost in reality? | Materials, equipment, travel and other needs, without confusing them with the tax allowance | | What evidence supports my next step? | A current official source or case-specific advice, not just a familiar label |
Try writing your proposed activity in one plain sentence without using “freelancer,” “micro” or “small business.” Then list one cost you know and one rule you still need to verify. This does not determine eligibility. It makes the next conversation with an adviser or authority more concrete.
The essential idea is simple: a micro-entrepreneur is not someone operating outside the normal responsibilities of a business. They use a simplified framework for specified purposes. Understanding that framework means separating the legal person, the calculation rules and the practical business—not treating the word micro as an answer to all three.